If you have ever wondered how to stop overspending, you are in good company. Most of us blow past our own limits now and then, and it rarely comes down to being “bad with money.” Overspending is usually a mix of habit, emotion, and a shopping world built to make buying effortless. The good news is that a few honest changes can quietly put you back in charge, with no shame or extreme budgeting required.
Table of Contents
Why We Overspend (It’s Not Just Willpower)
Before we get to the fixes, it helps to understand what is actually happening. Overspending is rarely a moral failing. It is your brain doing exactly what it evolved to do: chase a quick reward. A new purchase gives a small, genuine buzz, and once that fades, the cost hangs around long after the excitement is gone.
On top of that, modern shopping is engineered to be smooth. Saved cards, one-tap checkout, and “only 2 left” nudges all remove the natural pauses that used to make us think twice. When buying is this easy, emotional spending slips in almost unnoticed.
There is also lifestyle creep — the slow way our spending rises to match whatever we earn. A raise arrives, and somehow the money is already spoken for. None of this makes you weak. It just means the deck is stacked, and knowing that is the first advantage.
It also helps to know how common this is. Plenty of people who earn comfortably still overspend, and plenty who earn little still manage to save. Income is only part of the story. You do not need a personality overhaul to change course, either. Small, repeatable adjustments tend to outperform bursts of extreme discipline that fade within a week or two.
Common triggers to watch for
- Feeling stressed, bored, sad, or celebratory
- Late-night scrolling with a card already saved
- Sales and “limited time” countdowns
- Trying to keep up with friends or social feeds
- Shopping as a reward after a hard day
Notice that almost none of these triggers are really about the item itself. They are about a feeling you want to change or a moment you want to mark. That distinction matters, because it means the fix is usually emotional, not financial. Once you can name the feeling underneath the urge, you can meet it in a way that does not cost you anything at all.
How to Stop Overspending by Naming Your Triggers
The first real step in how to stop overspending is noticing the moment right before you buy. What were you feeling? Where were you? Awareness sounds soft, but it is the lever everything else rests on. You cannot interrupt a pattern you have never seen clearly.
Try a simple experiment: for the next 30 days, jot down every unplanned purchase and one word for the mood behind it. Most people are quietly surprised by the total, and that surprise alone tends to shift behavior. You are not judging yourself here — you are gathering evidence.
Once you spot your patterns, you can plan around them. If stress sends you to your cart, line up a free alternative in advance: a walk, a call, ten minutes of music. The goal is to give the feeling somewhere to go that is not the checkout page. For a broader look at spending habits, the U.S. government’s Consumer Financial Protection Bureau offers free, non-commercial tools worth bookmarking.
- Track unplanned buys for 30 days, mood included.
- Circle your top two or three triggers.
- Pick a free swap for each trigger before it strikes.
- Review the list weekly and adjust.
Keep the tracking low-effort so you actually stick with it. A notes app, a scrap of paper by the door, or a simple spreadsheet all work fine. The point is not precision to the penny; it is spotting the handful of situations that drive most of your unplanned spending. For many people, just two or three settings account for the bulk of it.
Awareness also compounds. The more often you catch yourself in the moment, the easier it becomes to pause before the next purchase. What feels like real effort in week one usually settles into a quiet, almost automatic habit by week four or five. You are training attention, and attention is a muscle that strengthens with steady, forgiving practice.
Add Friction Between You and the Buy Button
If frictionless shopping is the problem, deliberate friction is the cure. The idea is simple: make impulse buys just annoying enough that your slower, wiser brain gets a say. A few extra seconds of effort often turns a want into a shrug.
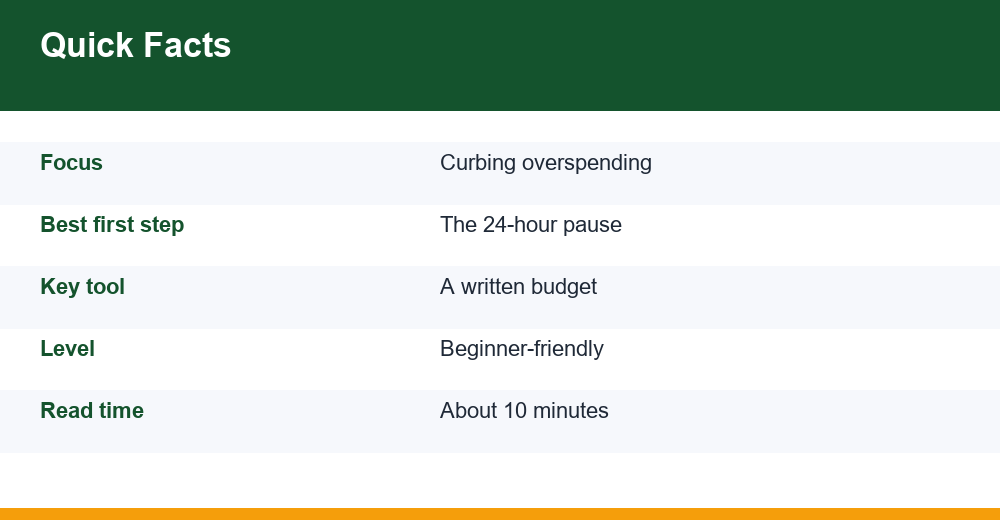
The best-known trick here is the 24-hour rule. When you feel the urge to buy something non-essential, put it on a wait list and sleep on it. If you still want it tomorrow, and it fits your plan, buy it with a clear conscience. Most urges simply pass.
- Delete saved cards so checkout takes real effort.
- Turn off one-click and one-tap buying.
- Unsubscribe from store and sale emails.
- Unfollow accounts that make you want to spend.
- Leave your card at home for a shopping-free day.
- Cancel auto-renewals you did not choose on purpose.
None of these require willpower in the moment — that is the point. You set them up once while you are calm, and they quietly protect you later when you are tired, stressed, or tempted.
You can even build friction into your calendar. Pick one or two no-spend days each week, when you buy nothing beyond genuine essentials. It is not about deprivation; it is about proving to yourself that the urge to spend passes on its own. Over time, those small, repeated wins rebuild trust in your own judgement, which is worth more than any single saved dollar.
Think of friction as a favour to your future self. The version of you setting these barriers up is calm and clear-headed. The version who runs into them later, worn out after a long day, gets to lean on that earlier decision instead of relying on willpower that is already running low. You are simply choosing when to decide.
Give Every Dollar a Job
A budget is the backbone of how to stop overspending, because it turns a vague “I should spend less” into a clear plan you can actually follow. When every dollar has a job — bills, saving, and yes, guilt-free fun — you always know whether a purchase fits or not.
You do not need a complicated system. A simple split of needs, wants, and savings is enough to start. If you are building one from scratch, our guide on how to make a budget walks you through it step by step, and these budgeting tips help it survive real life.
Crucially, leave room for small pleasures. A budget with zero fun is a diet you will quit by Friday. The aim is not to punish yourself; it is to spend on what you value and stop leaking money on what you do not even remember buying.
A quick way to test any purchase
- Is this a planned buy or a reaction to a mood?
- Does it fit this month’s budget without borrowing from another goal?
- Will I still be glad I bought it next week?
Revisit the plan every month, because life keeps moving. A budget is not a stone tablet; it is a rough forecast you refine as you learn. If one category keeps blowing up, that is usually a sign the number was unrealistic, not that you failed. Adjust it, give yourself a little more breathing room, and build a plan you can genuinely live with.
If numbers stress you out, keep it visual instead. Three jars, three bank pots, or three lines on a page can do the same job as any app. The tool matters far less than the habit itself: checking in before you spend, not after the money has already gone. Pick whatever version you will actually open and use each week.
Smarter Swaps That Still Feel Good
Cutting spending does not have to mean going without. Often it just means swapping an expensive habit for a cheaper version that scratches the same itch. Small, repeatable swaps usually beat one dramatic sacrifice you cannot keep up.
The table below shows a few everyday swaps. The figures are illustrative examples only — your real numbers will differ — but they show how modest changes can quietly add up over a month.
| Instead of | Try this | Rough monthly saving* |
|---|---|---|
| Buying coffee out daily | Brew most days, treat on Fridays | $60 |
| Impulse online carts | Use a 24-hour wait list | $40 |
| Forgotten subscriptions | Cancel two or three you never use | $25 |
| Lunch bought every day | Pack lunch three days a week | $70 |
*Illustrative figures for the sake of example, not a promise or a guarantee. Your own savings depend entirely on your habits and prices where you live.
Aim for swaps you barely notice. If cutting something out entirely leaves you feeling deprived, you will likely rebound and overspend later to make up for it. A gentler version of the same pleasure — one really good coffee a week instead of five hurried ones — tends to stick, because it still feels like a treat rather than a punishment.
The real win is repetition. A single grand gesture, like canceling everything and going cold turkey, feels impressive but rarely lasts. Two or three small swaps you keep for months will almost always beat one dramatic week you abandon. Pick the swaps that feel easy first, and let those early, low-effort wins build your momentum for the harder ones.
Turn Cutbacks Into Something You Can See
Once you know how to stop overspending, the money you free up can vanish just as quietly as it used to — unless you give it a destination. Cutting back only feels worth it when you can watch the payoff grow somewhere.
A practical move is to save the difference automatically. When you cancel a subscription or skip a habit, set up a small transfer for the same amount to a savings account on payday. You never see it, so you never miss it, and the progress becomes real.
Give that money a name that means something to you — an emergency cushion, a trip, a debt you want gone. A goal you care about is far more motivating than a vague pile of cash. Our guide on how to save money covers easy ways to make saving close to effortless.
- Automate a transfer the day you get paid.
- Name each savings goal clearly.
- Start tiny — consistency matters more than size.
- Check your progress monthly for a quick morale boost.
If your emergency cushion is solid and you want your money to grow further, investing is a common next step — but it carries risk, and the value of investments can fall as well as rise. There are no guaranteed returns, so it is wise never to invest money you might need soon, and to consider speaking with a qualified financial professional before you begin.
Watching the balance climb becomes its own kind of motivation. Every transfer is quiet proof that the changes are working, which makes the next one easier to keep. Money that once slipped away without a trace now has somewhere to be and a reason to stay there. That visible progress is often what carries people through the slower weeks.
What to Do When You Slip (Because You Will)
Here is the part most advice skips: you will slip up, and that is completely normal. Learning how to stop overspending is a skill you build over time, not a personality test you pass or fail. One splurge does not undo your progress unless you let it snowball into a guilt spiral.
When it happens, skip the shame. Instead, get curious. What triggered it? Was the budget too tight to be realistic? A slip is just data — useful feedback about where your plan needs a small tweak, not proof that you are hopeless with money.
Then simply pick up where you left off. Adjust the next week, not your whole self-image. People who stick with better money habits are not the ones who never mess up; they are the ones who forgive the mistake quickly and keep going.
Progress in this area is rarely a straight line. Some months will look great; others will wobble because of a holiday, a repair, or a rough patch. What matters is the overall direction across a year, not any single week. Judge yourself gently and by the long-term trend, and you are far more likely to keep going.
This article is general educational information, not personalized financial advice. Everyone’s situation is different, so consider your own circumstances and, for bigger decisions, talk with a licensed or qualified financial professional you trust.
Frequently Asked Questions
What is the fastest way to stop overspending?
Start with the 24-hour rule: pause any non-essential purchase for a day. This single habit interrupts most impulse buys almost instantly, and it costs nothing to try. Pair it with deleting saved cards so checkout takes real effort.
Why do I keep overspending even when I earn enough?
Often it is emotional spending or lifestyle creep, not a lack of income. Stress, boredom, and easy one-tap checkout all quietly nudge you to buy. Tracking your spending for 30 days usually reveals the real patterns behind it.
How do I stop overspending without giving up all my fun?
Build a little guilt-free spending into your budget on purpose. A plan with zero enjoyment rarely lasts. The goal is to spend intentionally on what you truly value and cut the forgettable purchases you would not miss anyway.
Is overspending a sign of a bigger problem?
Occasional overspending is very common and usually fixable with small habit changes. But if spending feels compulsive, causes real distress, or you cannot stop despite harm, it is worth speaking with a qualified professional or counselor for support.